Munis vs Annuities
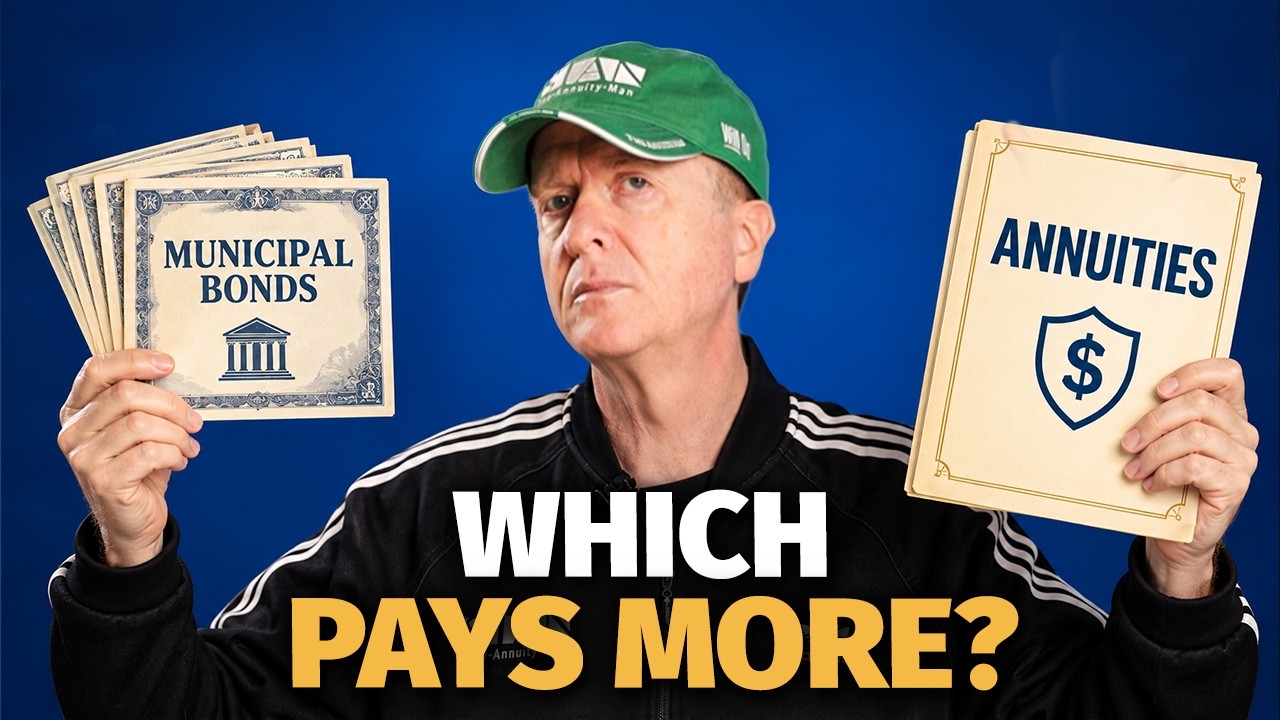
Can municipal bonds and annuities both help protect your money while providing guaranteed yields? In this video, let's compare municipal bonds (munis) with multi-year guarantee annuities (MYGAs), explaining the key differences in tax treatment, principal protection, guaranteed interest, and investment terms. Learn why MYGAs may be worth considering as a complement to municipal bonds, how their tax-deferred growth differs from the tax-free interest of munis, and why not all annuities offer the same contractual guarantees.
▶️ WATCH NEXT: https://youtu.be/tc3METYN5nk
Watch and Enjoy!
Stan The Annuity Man
Key Moments in this Episode
========================
00:00 Introduction to the Video
00:40 My Experience Managing Municipal Bonds
02:19 Annuity Product Similar To Munis
03:17 How Munis Are Harder To Get Today
04:14 Truth About Index Annuities
05:09 The Only Comparable Annuity Product To Munis
07:19 Helpful Annuity Resources
07:44 Next Video To Watch
What To Watch Next:
========================
https://youtu.be/tc3METYN5nk
Resources
========================
📞 Book a Free 30-minute Call with The Annuity Man Team:
https://www.stantheannuityman.com/book-a-call
📘 Get Your FREE Annuity Owner’s Manual:
https://www.stantheannuityman.com/get-smarter/annuity-books
🔢 Use Our FREE Annuity Calculators + Live Rate Feeds:
https://www.stantheannuityman.com/
🎧 Listen to the Fun With Annuities Podcast:
https://youtube.com/@funwithannuities
Learn More About Stan The Annuity Man
========================
Stan The Annuity Man® is known as “America’s Annuity Agent®” and the top independent annuity agent in the United States, licensed in all 50 states. He is a firm believer that annuities should NOT be purchased for market growth and is focused on educating the consumer so that they can make an informed decision on their terms and on their time frame. Stan has published 7 books on the annuity topic and prides himself on being a consumer advocate for all things annuity.
========================
Video by Nate Woodbury
BeTheHeroStudios.com
http://YouTube.com/c/NateWoodbury
#StanTheAnnuityMan
#Annuity
#TheAnnuityMan
#Retirement
0:00
Hi there, Stan the Annuity Man.
0:01
America's annuity agent, licensed in all
0:03
50 states in Puerto Rico, founder of
0:05
CGO. Contractual guarantees only, which
0:07
means that you own an annuity for what
0:09
it will do, not what it might do, not
0:11
the hypotheticals and theoreticals, all
0:14
the too good to be true sales pitches
0:16
that are out there that are too good to
0:18
be true. Period. Today's topic is a good
0:20
one, and I have some foundational
0:21
knowledge here to weigh in. Munis versus
0:25
annuities. So, municipal bonds versus
0:27
annuities. Stan, is there a correlation
0:30
to that? We'll talk about that after
0:33
this.
0:38
[music]
0:40
All right. So, I know what you're
0:41
saying, Stan the Annuity Man. You're
0:42
talking about municipal bonds. Well, I
0:44
did have a previous life before coming
0:46
the incredible mythical figure Stan the
0:50
Annuity Man. I used to work for Dean
0:51
Witter, Payne Weber, UBS, and Morgan
0:54
Stanley. And um [clears throat]
0:57
one of my specialties was municipal
0:58
bonds and I manage those at a very high
1:01
level. I do understand them backwards
1:03
and forwards. I'm old enough to remember
1:05
when municipal bonds were offered in the
1:07
paper. Remember that you'd get your
1:09
paper, they'd have [clears throat] an
1:11
offering for the, you know, the city
1:13
water and sewer bond paying X
1:15
percentage, etc. The cool thing about
1:18
munis is they're taxfree. So tax-free
1:22
yield on those bonds. I was working with
1:25
Morgan Stanley. This is still in my
1:27
brain because every single year I have
1:30
at least one old Morgan Stanley customer
1:32
send me a thank you note. And the thank
1:34
you note is for the municipal bonds that
1:37
I was selling back then during the.com
1:39
error era error era erra. Um
1:44
[clears throat] that were 6% tax-free
1:47
AAA insured municipal bonds. I know for
1:50
you bond buyers out there, you're like,
1:52
"What?" I could barely give them away
1:55
because everybody wanted to do the com
1:57
stocks, but 6% taxfree for a redneck
2:00
like me was like, "That sounds pretty
2:02
good." Because the taxable equivalent
2:03
yields like over 9%.
2:06
It's pretty good. To this day, people
2:08
that bought them a while back um and
2:11
still because they weren't callable are
2:13
still getting 6% tax-free income yield
2:16
off of that. Okay. Is there anything in
2:19
the annuity industry that does that
2:21
stand the annuity man? And the answer is
2:23
no with an asterisk. Okay. Now, a
2:27
municipal bond is a guaranteed yield and
2:31
the underlying value is guaranteed if
2:34
you hold it to maturity. Okay. In the
2:36
annuity world, there's a product called
2:38
a multi-year guarantee annuity. It's the
2:40
annuity industry version of a CD. I call
2:42
it an annuity bond, which is the reason
2:44
we're talking today. It's annuity bond
2:47
because the underlying value is
2:48
protected similar to munis. Okay. The
2:51
yield is guaranteed similar to munis but
2:54
it's not tax-free unless you use the
2:57
MIGA inside of a WTH and then it would
3:00
be.
3:02
Now am I telling you to do that? Put
3:05
your put MAS inside of a Roth. No. But
3:07
I'm saying you could. And then the um if
3:10
you took out the interest, that interest
3:12
would be taxfree because you've already
3:14
paid the taxes to make it a Roth IRA.
3:16
Now, the interesting part, my my two
3:18
partners are still from the old days at
3:20
Morgan Stanley. They're still slogging
3:22
away at at the big firm, you know, they
3:24
got the big 401k. Um I had, you know,
3:26
I'm entrepreneur. I had to come out here
3:28
and do this because I saw the
3:30
opportunity and it worked out worked out
3:31
for all of us. Um and I'm still good
3:33
friends with them. But they're telling
3:34
me now right now the the munis are hard
3:36
to get. back in the day, we could get
3:38
them for people. Um, I think all of the
3:40
institutions, private equity, family
3:42
offices are buying up most of the the
3:45
good municipal bonds out there. Um, so
3:48
you're really kind of stuck. You can't I
3:50
guess you could buy bond funds. Um, but
3:52
that that's a whole another story. And
3:55
by the way, I used to have a securities
3:56
license for decades. I don't have that
3:58
anymore. So I don't even do munis. Um, I
4:01
don't do anything uh in the security
4:03
side because I don't have to. I sell
4:05
contractual guarantees on the life
4:07
insurance side that life insurance
4:08
companies issue annuities. Can munis and
4:11
and mas work together? Yes. Are there
4:14
any other type of annuities that could
4:18
be equated into or compared with
4:22
logically or rationally with immunity?
4:24
The answer is no. But there's going to
4:26
be people out there that are going to
4:28
tell you an index annuity is like a
4:29
bond. They're wrong. And there's some
4:32
smart people that said that and they're
4:34
wrong. Both munis and mas have
4:36
guaranteed yields. Index annuities do
4:40
not have guarantees. I heard a guy the
4:42
other day, well, I'm going to buy a RIA
4:43
registered index linked annuity, which
4:45
is a security instead of munis. I'm
4:46
like, it's not guaranteed. Munis are
4:49
guaranteed. That's apples and oranges.
4:51
Well, this guy said I could get this
4:53
could said you could or you will.
4:57
Remember, you own an annuity for what it
5:00
will do, not what it might do. Not the
5:01
hypothetical,
5:03
not the theoretical, not the back test
5:04
of Mr. Jones, if you'd owned it 10 years
5:06
ago, you'd gotten this. That's garbage.
5:09
So when you go munis versus annuities,
5:11
it's really munis in one product called
5:13
a multi-year guarantee annuity. That's
5:16
the only thing that's even in the
5:17
category. Everything else is a force.
5:20
Everything else is a commission play.
5:22
Everything else is a square peg into a
5:23
round hole. Period. I know I used to
5:26
manage munis and I'm now out here in the
5:29
annuity space and I know annuities
5:31
backwards and forwards. I've forgotten
5:33
more than 99% of most agents
5:37
and there's nothing but migas that can
5:39
compare to munis and even then
5:43
migas and a wroth taxfree munis taxfree
5:46
and I love munis
5:48
you know if I you know one of the
5:50
reasons that uh I decided to leave you
5:53
know the big firms for to become stand
5:55
the annuity man is I love the
5:56
contractual guarantees out here but also
5:59
too it was kind of a moment in time
6:01
where mun companies were not more as
6:04
accessible to us as the brokers and for
6:08
the for our clients. And that was
6:09
upsetting to me because I really
6:11
believed in the in the MUN story and the
6:13
tax-free yield that you could get. I
6:15
mean, it's fantastic.
6:18
But in this world over here, multi-year
6:19
guarantee annuities have very good
6:21
yields. They're contractual. The
6:23
underlying value of a MIGA does not
6:25
fluctuate. Sometimes the in the MUN
6:27
world that does fluctuate but if you
6:29
hold it to term you're going to get you
6:31
know what you put in is I mean that's
6:32
it's principal protected but it does
6:34
fluctuate some during the duration with
6:36
MAS it does not that didn't make them
6:39
better. I'm just telling munis versus
6:41
annuities. It's really munis versus
6:42
migas and both of them you can take you
6:45
know the yield off the top and never
6:46
touch the principal if you want to do
6:48
that for in for income but they can work
6:52
together you know if if you have a good
6:55
advisor that can find those for you and
6:57
I'm not talking about mun mun funds I'm
6:59
talking about mun standalones there used
7:02
to be firms that just sold that I don't
7:03
know if they're even in business anymore
7:06
but you know multi-year guarantee
7:08
annuities you can buy durations 1 2 3 4
7:10
5 6 7 8 9 10. You know, obviously
7:13
durations on the MUN side can vary as
7:15
well and go out as far as 30 and 40
7:17
years. Do me a favor, go to my site at
7:20
theanuityman.com. Top right hand corner,
7:22
you're going to see see live rates.
7:23
You're going to see all the you can
7:24
click that, put in your state, put in
7:26
the duration, see the live mafs. Just
7:28
take a look at those. Those are very,
7:29
very good CD like annuity bond is what I
7:33
call them products. You can also
7:35
schedule a call with me. You can also
7:37
send me an email. You can download books
7:39
that I've written, owners manuals on
7:40
MAS. I have one on MAS that you can do
7:42
as well. Do me one last favor. Above my
7:45
above my head's a spinning clock and um
7:48
I did a video on just a lot of the
7:50
technology that we're doing. Talked
7:52
about virtual Stanley and Virtual
7:53
Stanley is an avatar we have on the site
7:55
that you can ask questions to 247365 and
7:58
you get my answers because we fed all my
8:00
videos, books, and articles into Virtual
8:02
Stanley. So he talks like me. So 247365
8:06
you can talk to him or you can schedule
8:08
call with me so you get the real Stanley
8:10
or virtual virtual Stanley if you want
8:11
to do an application and purchase
8:13
something become a client you can use us
8:15
for the application or you can do the
8:17
application online you also can go to my
8:20
site and run quotes anonymously without
8:23
putting in your name, email or phone
8:24
number and get real quotes. These aren't
8:26
estimates. These are real quotes coming
8:28
from the carriers fed into my site.
8:30
We're the only ones that do that and
8:31
don't require you to sign up. I'm not
8:33
building a database. I want you as a
8:34
client. You're smart enough to make your
8:36
own decision. I just want to give you as
8:37
much information as possible on your
8:39
terms and on your time frame. Okay? So,
8:41
munis versus versus annuities. It's
8:43
really munis versus migas. Multi-year
8:45
guarantee annuities. Both are very good.
8:47
Both I love. One I recommend, which are
8:50
migas. All right. My name is Stan the
8:53
annuity man. We'll see you next time.

Talk to Stan The Annuity Man® himself
Get Stan for 30 minutes. No cost for his 3 decades of experience. Prepare yourself for the brutal annuity truth.