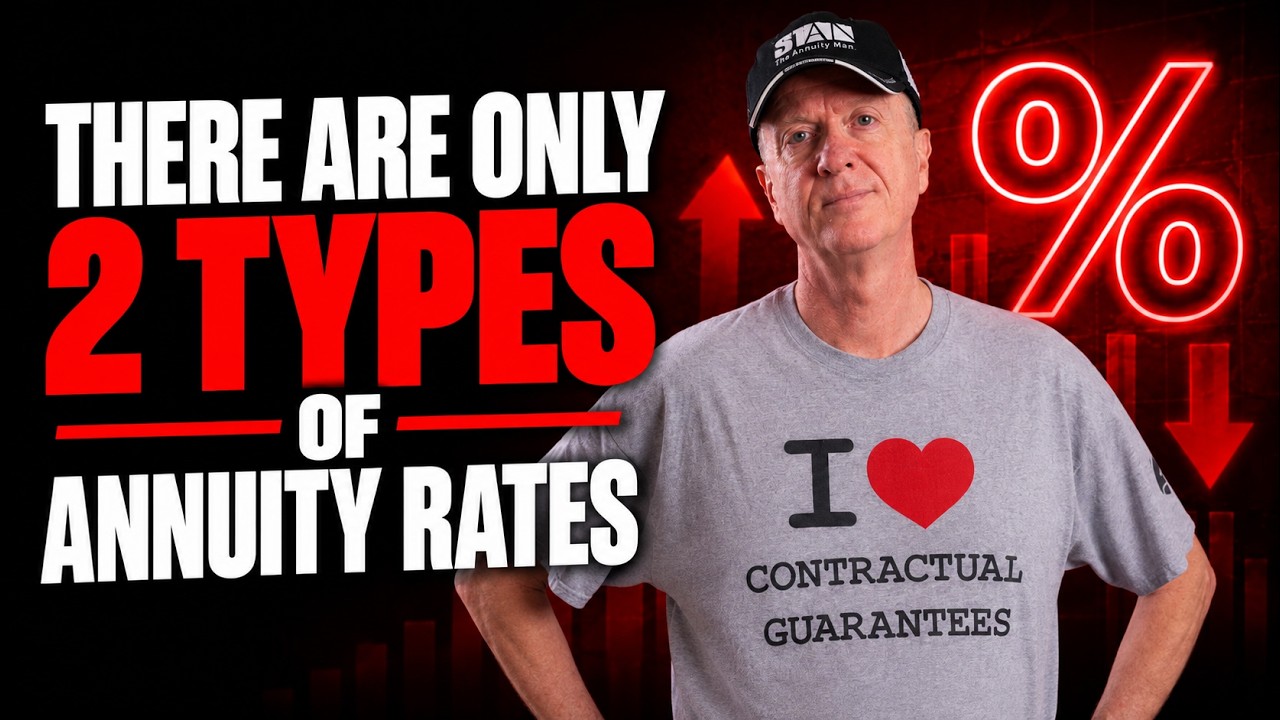
There Are Only 2 Types of Annuity Rates: Shootin’ It Straight With Stan
Book a Free 30-minute Call with The Annuity Man Himself:
https://www.stantheannuityman.com/book-a-call-with-stan?utm_source=youtube&utm_medium=organic_social&utm_campaign=video_description
Use Our FREE Annuity Calculators + Live Rate Feeds:
https://www.stantheannuityman.com/?utm_source=youtube&utm_medium=organic_social&utm_campaign=video_description#quick-quote
Get Your FREE Annuity Owner’s Manual:
https://www.stantheannuityman.com/learn?f4325255_type_equal=books&f4325255_sort_date=desc&utm_source=youtube&utm_medium=organic_social&utm_campaign=video_description#hub
What if the cash sitting in your checking account could compound year after year without the IRS taking a cut of the interest every year? Stan, The Annuity Man, explains how Multi-Year Guarantee Annuities make that possible.
In this episode, The Annuity Man discussed:
- The PILL framework: principal protection, income for life, legacy, long-term care
- MYGAs as the annuity industry's version of a CD
- Tax-deferred compounding for non-qualified money
- Taking interest out, turning it on and off, and moving to a new MYGA without paying tax
- Why MYGA rates can be higher than CD rates
Key Takeaways:
- Buy an annuity for what it will do, not what it might do. Annuities are contracts that shift risk to the insurer. They aren't tools for market growth.
- CD and money market interest is taxed every year. MYGA interest in a non-qualified account grows and compounds with taxes deferred.
- You don't have to take anything out when the term ends. You can move the money into another MYGA without paying tax, and it keeps compounding.
- Need income for a while? You can take interest off the top and keep your principal, then switch the payments off when you no longer need them.
- MYGA rates can beat CD rates because insurance companies back them with other profit centers. That doesn't make MYGAs better than CDs. It just makes them a strong fit for non-IRA cash.
"Multi-Year Guarantee Annuities - it is the biggest no-brainer of all time and the greatest example of the eighth wonder of the annuity world which is compound interest." — Stan The Annuity Man
Watch and Enjoy,
Stan The Annuity Man
LISTEN/WATCH FUN WITH ANNUITIES PODCAST
https://www.youtube.com/@funwithannuities
#stantheannuityman
#annuity
#theannuityman
#retirement
#retirementincome
#retirementplanning
#annuities
0:00
Welcome to Shooting it Straight with
0:01
Stan. I'm your host Stan the Annuity
0:03
Man, America's annuity agent, licensed
0:04
in all 50 states in Puerto Rico. The
0:06
founder of CGO, contractual guarantees
0:09
only, which means you own an annuity for
0:10
what it will do, not what it might do.
0:12
Never buy an annuity for market growth,
0:14
potential hypothetical non-G guaranteed
0:17
returns. Annuities are contractual
0:19
guarantees that are issued by life
0:21
insurance companies. Do not buy the
0:22
hype. Market growth does not equate into
0:25
annuities. So, never buy an annuity for
0:27
market growth, a pitch, upfront bonuses,
0:29
all that stuff. Be smart. Um, you have
0:32
to think before you jump to these some
0:34
of these sales pitches. Hopefully,
0:36
you'll choose us. Go to my site at
0:38
theanuityman.com. You can run quotes
0:39
anonymously without putting in your
0:41
information and get real quotes.
0:43
Download my six owners manuals. Schedule
0:45
a call with me. Email me at
0:46
stantheanuityman.com.
0:49
Today's topic is there are only two
0:51
types of annuity rates. R a tees rate.
0:55
So people are always, you know, fixated
0:58
with the Fed and fixated with treasuries
1:00
and they've been trained by CNBC and Fox
1:02
Business or or Bloomberg or whatever
1:04
you're watching out there. Got to follow
1:06
the Fed, the Fed, the Fed, the Fed, the
1:07
Fed.
1:09
No, the annuity industry is a little bit
1:11
different because annuities solve for
1:14
four things. Principal protection,
1:15
income for life, legacy, and long-term
1:16
care. That acronym is PIL, principal
1:19
protection, income for life, legacy,
1:21
long-term care. And there's only two
1:23
questions to ask and answer to see if
1:26
you need an annuity. First, what do you
1:27
want the money to contractually do? And
1:29
number two, when do you want those
1:30
contractual guarantees to start? Not
1:32
hypothetical, not theoretical,
1:34
contractual. And from those answers, we
1:36
can point you to the solution uh
1:40
contractually that's going to provide
1:41
the highest number for you. Okay? But
1:43
when it comes to rates, annuities,
1:46
the first the first thing you need to
1:48
look at is lifetime income. So, lifetime
1:50
income, there's four types of products
1:53
in the annuity world. You can't just
1:54
say, "I hate all annuities, buy them."
1:56
Well, you already own one. It's called
1:57
Social Security. That's the best
1:58
lifetime income annuity with an
2:00
inflation writer on it on the planet.
2:02
You already own one annuity. It's called
2:04
Social Security. If your employer
2:06
provides a pension, now you own two.
2:08
Okay? But lifetime income is primarily
2:10
based on your life expectancy at the
2:12
time you take the payments. Interest
2:13
rates play a secondary role. Interest
2:16
rates play a secondary role. It's life
2:18
expectancy. give you an example that
2:20
that will correlate easily in your
2:22
brain. The higher payment for social
2:24
security is at 70 as compared to 65.
2:27
Why? Because you're older. Why? Because
2:29
you have less life expectancy,
2:31
which means that there's fewer projected
2:33
payments, which means those payments are
2:35
higher.
2:36
It's really that simple. People say,
2:38
"Well, I might I might wait till I'm,
2:39
you know, two years from now. Maybe I'll
2:41
get a higher a higher guaranteed
2:42
payout." You will get a higher guarantee
2:44
payout because you're older and you have
2:46
less life expectancy. I mean, it's
2:49
really that simple. So, when we're
2:51
talking about there's only two types of
2:52
rates when it comes to lifetime income,
2:55
it's a payout rate. Now, some there are
2:57
some sites out there that try to compete
2:58
with us. That's a joke. And they'll put
3:01
beside like an immediate annuity, 7.2,
3:03
7.3. That's not yield player. That's a
3:06
numerical reflection of your life
3:08
expectancy. Well, I'm literally looking
3:10
for a 7.8 on a on an immediate. Well,
3:13
then get older.
3:15
[laughter] If you're not getting it on
3:16
our quotes, then you're you're young.
3:18
You're you're too young to get it. It's
3:21
not interest, it's not yield.
3:24
So, with life expectancy, the first rate
3:27
I want to talk about and get you
3:29
clearheaded on, payout rate, payout rate
3:33
is the amount of money they're going to
3:35
pay for the for the rest of your life.
3:38
The other rate is like an interest rate.
3:41
Let me give you an example. Multi-year
3:43
guarantee annuities are the annuity
3:44
industry's version of a CD. I call them
3:47
annuity bonds because you're buying a
3:49
specific duration with a specific life
3:51
insurance company and they're
3:52
guaranteeing an interest rate for that
3:54
duration. So, for example, you can say,
3:56
I want a five-year multi-year guarantee
3:59
annuity and it's yielding this and
4:02
they're going to guarantee that for that
4:04
5-year time period and and you can go to
4:06
my site and pull up a live feed of the
4:08
best fixed rates on the planet. Not do
4:10
you don't have to put in any information
4:12
just your state and you just pull the
4:13
duration and you'll see you can buy one
4:15
year, two year, three year, four year,
4:17
five year, six year, seven year, 8year,
4:19
9year and 10year ma contractual
4:22
guaranteed rates.
4:24
Those are rates. They work like CDs.
4:27
They work like bonds. They pay an
4:29
interest rate for a specific period of
4:30
time that you choose. You can ladder
4:32
them. You can buy three, five, seven,
4:34
10. You can do whatever you want. But
4:36
that's a rate. That's an interest rate.
4:40
Whereas with lifetime income, that's not
4:42
an interest rate. That's a payout rate.
4:44
So those are the two rates. Interest
4:46
rate, payout rate. Completely separate
4:49
animals. Cons completely separate
4:51
things.
4:54
Okay? Both of them are transfer of risk.
4:56
You're transferring the risk to the
4:58
Migas for the interest rate guarantee
5:00
locked in for the lifetime income.
5:02
You're transferring the risk for them to
5:05
pay you for the rest of your life. this
5:07
joint life for the rest of both of your
5:09
lives as long as one of you is
5:10
breathing.
5:12
But those are the rates.
5:14
Now, once again, you can go to my site.
5:16
You can run the the lifetime income
5:18
quotes like income writers. All you have
5:20
to put in is your state of residence,
5:23
gender, and your date of birth. No name,
5:25
no email, no phone number. We're the
5:27
only ones that do that. Period. We will
5:29
be the only ones to ever do that because
5:30
for whatever reason, everyone else is in
5:32
the data collection business. I'm not.
5:34
I'm in the annuity education business to
5:36
hopefully attract you as a client
5:38
because we're educating you and we're
5:39
being transparent and we're shooting it
5:41
straight.
5:43
Same thing with the MAS. MA is live feed
5:45
of all carriers. And by the way, I don't
5:48
I'm never going to mention a carrier
5:49
name because I don't care. For lifetime
5:51
income, it's A+ or better. No
5:52
exceptions. A+ or better for lifetime
5:54
income. We're going to marry that
5:56
company for the rest of your life.
5:58
Multi-year guarantee annuities, we're
6:00
going to date them. We're going to date
6:02
them for the duration. So, it might be
6:03
less than A+, but I'm going to sign off
6:05
on it. And I've batted a thousand%.
6:08
In my career, and that's decades, okay?
6:11
But don't be confused about the Fed and
6:13
all this stuff. I get people all the
6:15
time, well, I'm tracking the Fed. I'm
6:16
going to time it. I'm gonna time the No,
6:18
you're not. You're not going to time it.
6:20
I'll give you an example. My wife and I
6:22
buy MAS because Annuity Man is the the
6:25
company is a growth stock. Best growth
6:26
stock you can't buy because it's private
6:28
and I own it. But with our additional
6:30
money, we buy MAS. we want and we buy it
6:32
with nonIRRA money. And by the way, with
6:34
both of these products, the with the
6:37
rates, interest rates, and then payout
6:38
rates. You can use any type of account,
6:40
IRA, nonirra, Roth IRA, just all that
6:43
does is determine the taxation of the
6:44
money coming out. But my wife and I buy
6:47
these MAS, and we don't get it right all
6:49
the time. There just recently we
6:51
purchased a couple MAS and the two
6:53
companies we bought, rates went up after
6:56
we bought them, you know, like 60 days
6:58
after we bought them. Okay, great. I
6:59
can't time it. I'm not going to time it.
7:01
I'm not going to try to time it. At the
7:03
time of this taping, I rates both sides,
7:06
interest rates, payout rates are fair
7:08
and they highest they've been in a long,
7:10
long time. Bell doesn't ring at the top
7:12
or the bottom player. You know, if it's
7:14
fair and I told my wife the same thing.
7:16
Hey, that's a great company. It was a
7:17
fair um guarantee and we went with it
7:20
and I'm good and I'm not looking in the
7:22
rearview mirror. But what I want you to
7:24
do though is realize that interest
7:27
rates, the Fed, whoever, whoever's in
7:30
charge,
7:32
it's not linear
7:34
like it is with the markets a lot of
7:36
times. A lot of times you would think
7:37
like MIA companies that if interest
7:39
rates raised or lowered that it would
7:41
follow. Sometimes it does, sometimes it
7:44
doesn't. Same thing with lifetime
7:45
incomes. Sometimes it does, sometimes it
7:47
doesn't. You go say, "Well, wait a
7:48
minute. Why? Why wouldn't interest rates
7:51
positively affect every single company?
7:52
If that company doesn't want your age
7:54
range, they're going to lower the
7:55
guarantee not to attract you. If they
7:57
have enough of you in their actuarial
7:59
pool that they're pulling the risk,
8:01
they're not going to they're not going
8:02
to raise the rates to attract you. Same
8:04
thing with MAS. If they have raised
8:06
enough money and interest rates go up,
8:08
that doesn't mean they're actually going
8:09
to go up. They might go down with that
8:12
specific company, okay, to not attract
8:15
you. That's the reason I always say
8:17
annuities are commodity products.
8:18
Shopping all carriers for the highest
8:20
contractual guarantee. On both sides of
8:22
that ledger, rates for principal
8:24
protection, rates for payout. We're
8:27
shopping all carriers because somebody's
8:29
going to want your business. Somebody's
8:31
going to want to attract you. So there's
8:33
not one company that's better than the
8:35
other. All right? So just remember
8:37
there's two types of rates in the
8:39
annuity world. There's interest rates
8:41
for like MAS and then there's payout
8:44
rates for the lifetime income products.
8:48
And if you remember one thing in
8:49
addition to that is you shop all
8:51
carriers for the highest contractual
8:53
guarantee that you're looking to
8:54
accomplish contractually
8:57
not hypothetically. Do not buy annuities
9:00
for market growth. Listen to me. Buy
9:02
them for the contractual guarantees of
9:04
the policy in the story. Go to my site
9:06
theanuityman.com. One last thing,
9:08
there's a virtual Stanley. There's a
9:10
virtual me on the site. Bottom righthand
9:12
corner, you'll see the caricature. If
9:14
you click it, you get to ask Virtual
9:16
Stanley questions. And what we've done
9:18
with the company that is supporting this
9:20
great group of guys and gals from MIT
9:23
grads, they have fed Virtual Stanley the
9:25
2,000 videos and the 400 articles and
9:28
the seven books that I've written. And
9:29
the answers you're going to get are me
9:31
247365.
9:33
You can always schedule a call with me.
9:34
You can always email me at
9:35
stantheananuityman.com.
9:38
And we also have online applications as
9:40
well if you don't want to interact. Um,
9:43
you know, we we can take you I think 85%
9:45
of the way current rules in the annuity
9:47
industry, but we offer that as well. We
9:50
are the tech leaders out here, but yet I
9:52
this redneck still owns the company. How
9:54
about that? I just surround myself with
9:55
smart people. The guy that runs my
9:56
company's from Google. Uh, very smart.
9:58
So, we're we're teched out and we're
10:00
doing that to give you the options to
10:02
shop and get your questions answered
10:04
without having to talk to someone if you
10:06
do not want to do that. But you can you
10:07
can always take that off-ramp and go old
10:09
school and talk with us. My name is Stan
10:11
the Annuity Man. That is Shooting It
10:13
Straight with Stan. We'll see you next
10:15
time.
Talk to Stan The Annuity Man® himself
Get Stan for 30 minutes. No cost for his 3 decades of experience. Prepare yourself for the brutal annuity truth.