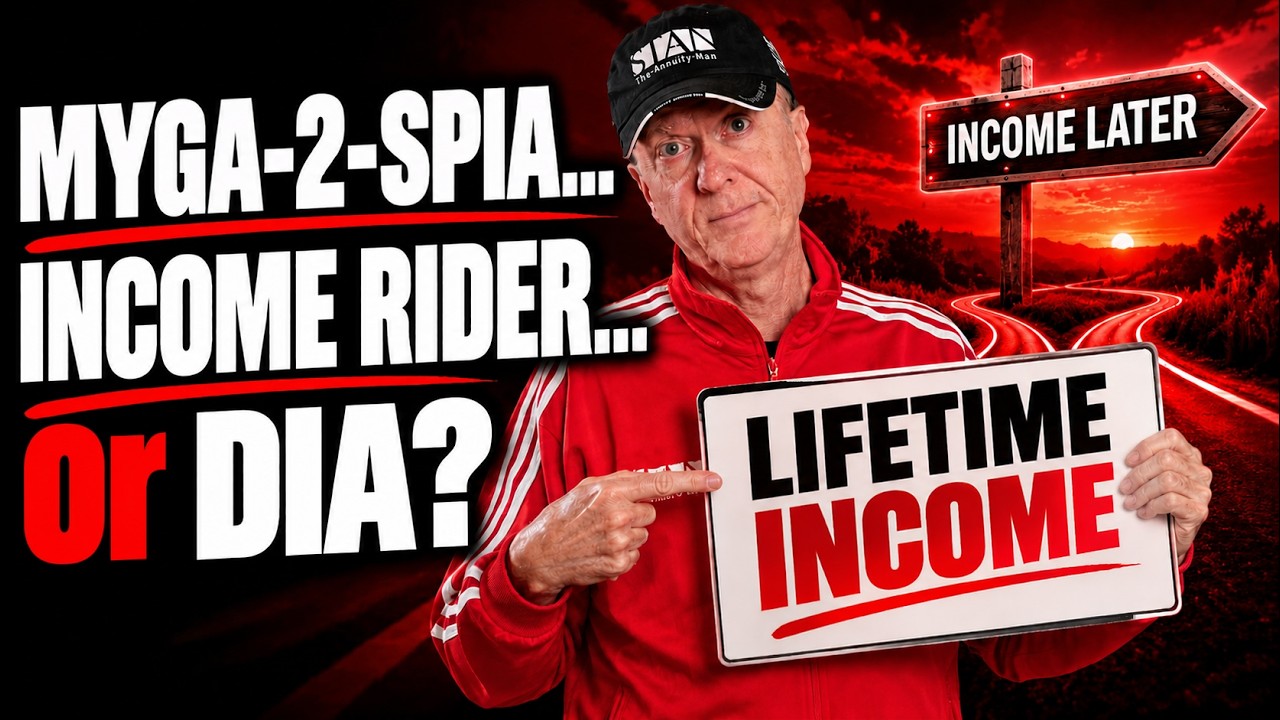
MYGA-2-SPIA…Income Rider…or DIA?: Shootin’ It Straight With Stan
Book a Free 30-minute Call with The Annuity Man Himself:
https://www.stantheannuityman.com/book-a-call-with-stan?utm_source=youtube&utm_medium=organic_social&utm_campaign=video_description
Use Our FREE Annuity Calculators + Live Rate Feeds:
https://www.stantheannuityman.com/?utm_source=youtube&utm_medium=organic_social&utm_campaign=video_description#quick-quote
Get Your FREE Annuity Owner’s Manual:
https://www.stantheannuityman.com/learn?f4325255_type_equal=books&f4325255_sort_date=desc&utm_source=youtube&utm_medium=organic_social&utm_campaign=video_description#hub
Planning to turn savings into lifetime income later? This episode compares three strategies and argues for evaluating them by the contractual guarantees they provide—not by projected returns or sales pitches.
In this episode, The Annuity Man discussed:
- The “PILL” purposes of annuities
- Questions to clarify income goals and timing
- Income Riders and their contractual guarantees
- Deferred Income Annuities and QLACs
- MYGA-to-SPIA as a way to defer an income decision
Key Takeaways:
- Start by defining what the money should contractually do and when the guarantees should begin.
- For future lifetime income, compare an income rider, a deferred income annuity, and a MYGA-to-SPIA strategy.
- No single strategy is best for everyone; the right comparison depends on the goal and whether the income needs to be locked in now.
- Evaluate guarantees separately from an indexed annuity’s non-guaranteed returns.
- Compare options and understand their trade-offs rather than being steered toward just one product.
"If you just look at the contractual guarantees, you're going to be fine." — Stan The Annuity Man
Watch and Enjoy,
Stan The Annuity Man
LISTEN/WATCH FUN WITH ANNUITIES PODCAST
https://www.youtube.com/@funwithannuities
#stantheannuityman
#annuity
#theannuityman
#retirement
#retirementincome
#retirementplanning
#annuities
0:00
Welcome to shooting it straight with
0:01
Stan. I'm your host Stan the annuity
0:02
man. America's annuity agent licensed in
0:04
all 50 states and Puerto Rico. Founder
0:07
of CGO contractual guarantees only. You
0:09
own an annuity for what it will do, not
0:12
what it might do. I encourage you go to
0:14
my site at stand theanuityman.com or
0:16
theanuityman.com. Both will get you
0:18
there and you can download books, run
0:20
anonymous quotes, uh talk to Virtual
0:22
Stanley 24/7 365, fill out applications.
0:26
If you find a quote that you like and
0:27
you want to lock in, you can do those
0:29
applications 24/7 365 or you can utilize
0:32
the best staff in the business here in
0:34
Las Vegas, Nevada. Today's topic is Ma
0:37
Despia
0:39
income writer or DIA rhymes. I know
0:42
you're saying Stan, you're so catchy.
0:44
Madpia, income writer, income writer or
0:47
DIA. I guess in the south you might call
0:48
it a income r income writer or dia.
0:53
So when you speak with us, we're going
0:56
to ask you two questions. Period. Every
0:58
single person. First question, what do
1:00
you want the money to contractually do?
1:03
And second questions, when do you want
1:05
the those contractual guarantees to
1:07
start? Again, what do you want the money
1:09
to contractually do? When do you want
1:11
those contractual guarantees to start?
1:14
Remember, annuities solve for four
1:16
things. Acronym is pill. P stands for
1:18
principal protection. I stands for
1:20
income for life. L stands for legacy.
1:22
and the other L stands for long-term
1:24
care. But let's go back to the two
1:26
questions. Let's just say, what do you
1:28
want the money to contractually do? And
1:29
you say lifetime income. Okay, follow-up
1:32
questions. When do you want that
1:34
lifetime income to start? And you say
1:37
down the road, two years, three years,
1:39
four years, 5 years, six years,
1:40
whatever, 10 years. Down the road,
1:44
you're down to three choices.
1:46
Period. Three. Not one. Not Johnny Apple
1:50
Seed Asian going, "Well, sir, you're
1:51
gonna get it. You have to get one of
1:53
these in index annuities with an upfront
1:55
bonus.
1:59
[sighs] There's other choices, of
2:00
course. So, let's go through them. Let's
2:03
go through Johnny Apples Seed Agents one
2:04
because that's the one you're going to
2:05
hear first and that's the one you're
2:07
going to call me about because it sounds
2:08
too good to be true. And that's the one
2:10
I'm going to walk you off the cliff and
2:11
say, "Please do not listen to that
2:13
garbage."
2:16
Income writers are a contractual
2:18
guarantee for lifetime income that ride
2:20
and get it income writer ride on top of
2:24
a policy. You can attach them to to a
2:27
couple of policies like a variable
2:29
annuity or an indexed annuity. But an
2:32
index annuity provides the we found
2:34
provides the highest contractual
2:35
guaranteed income writer amount.
2:39
Draw a line down a blank sheet of paper.
2:40
This side's the index side right here.
2:43
Non-g guaranteed returns. bad CD. We
2:46
don't care. We don't care. We don't
2:48
care. What we care about is on this
2:50
side. That's the income writer
2:52
contractual guarantee.
2:55
So, one of the quotes you're going to
2:57
get is an income writer quote. A+ or
2:59
better. No exceptions. No exceptions. Do
3:02
not bottom fish for lifetime income. A+
3:05
or better. And the highest number. We're
3:07
going to quote all A+ carriers for that
3:09
highest number. We could care less about
3:11
the logo, the name of the product, or
3:13
the whoever the the carrier is. A+ or
3:16
better, highest income writer number.
3:19
That's an income writer.
3:23
The second way is a deferred income
3:24
annuity. It's a it's a single premium
3:27
immediate annuity that you defer. Once
3:29
you're past a year, an immediate annuity
3:31
turns into a deferred income annuity.
3:33
And just to throw another wrench in the
3:35
engine, a qualified longevity annuity
3:37
contract is a deferred income annuity.
3:39
They can you can only use in a in an
3:41
IRA. Get it? Q qualified. But a deferred
3:45
income annuity is once again a lifetime
3:47
income stream that can start in the
3:49
future. You can defer it for as long as
3:50
you want. It's a pension. There's no
3:52
moving parts. There's no annual fees.
3:54
There's no market attachments. The big
3:56
boys play there. The A+ companies play
3:58
there. So again, you're looking for
4:00
income to start at a later date.
4:03
Deferred income annuity. That's a great
4:05
choice. And we're going to show you that
4:06
choice because we have to.
4:10
We're not going to steer you to a
4:11
product.
4:13
The reason that everybody's trying to
4:15
sell you an income writer with ind index
4:16
annuity is the highest commission
4:18
product on the planet. Doesn't make it a
4:19
bad product, but you have to show the
4:21
others. You have to explain the others.
4:23
The third way to do what I call income
4:24
later is what I what I have deemed and
4:27
created called MA to SPIA. A multi-year
4:31
guarantee annuity. MA is the annuity
4:33
industry's version of a CD. I call it an
4:35
annuity bond.
4:37
You're buying a piece of paper. You're
4:38
buying a guarantee from a life insurance
4:40
company. They're guaranteeing you an
4:42
interest rate for a specific period of
4:43
time.
4:46
So, MA got a SPIA. The SPIA is an
4:48
immediate annuity. Let me give you an
4:49
example of how that works. Hey Stan, I
4:52
want income to start in five years,
4:55
but I'm really not sure I want to do
4:57
that. But I want I want to have the
4:59
ability to do that.
5:01
Okay, let's buy a five-year MA. you're
5:03
going to know exactly what that
5:04
compounding interest rate is going to be
5:05
for those 5 years. And at the end of the
5:08
5 years, we can then shop for the
5:10
highest contractual guaranteed immediate
5:12
annuity at that time and then transfer
5:15
that money non-t taxable event to the
5:17
immediate annuity.
5:19
And that can be done in nonirra, IRA and
5:22
Roth IRA.
5:25
Deferred income annuities can be done in
5:28
nonirra, IRA, Roth IRA. If it's in IRA,
5:31
the deferred income annuity becomes a
5:33
CQAC. It's one and the same.
5:36
Income writer, you can do it in nonirra,
5:38
IRA, Roth IRA. All of these products,
5:41
all of these strategies, all of these
5:43
contractual guarantees can be used in
5:45
every single account type. Can it be
5:47
used in a Roth? Yes. Can it be used in
5:48
IRA? Yes. Can I roll my for 401k into
5:51
it? Yes. Can use my checking account
5:53
money? Yes.
5:57
The guarantees are the same. The
5:59
taxation of the money coming out would
6:00
be different,
6:02
right?
6:04
Taxation of the money of a traditional
6:05
IRA coming out of a traditional IRA is
6:07
going to be different than a Roth.
6:11
Common sense.
6:13
So, you're going to have to tell us or
6:14
if you're on the site, you can run the
6:16
quotes. Just put in what type of account
6:18
it is.
6:20
But when you're looking for income
6:22
later, there's three choices. Maispia,
6:26
income writer, or DIA. again MA to SPIA
6:30
income writer income writer or DIA
6:38
and and
6:40
this the qu that that statement and that
6:43
fact and those three solutions the
6:46
question that you're always going to ask
6:48
me and and if anyone says they have the
6:51
answer they're full of crap Dan which is
6:53
the best one of those three which is the
6:56
best one there's the That's one. It
6:59
comes down to what you're trying to
7:01
solve for. It comes down to if you want
7:03
to lock in the g the uh the lifetime
7:06
income now at a future date. MPIA,
7:09
you're not sure, but you can dia an
7:12
income writer. You're locking it in for
7:14
a future date. And that that locked in
7:16
future income is to the penny and it's
7:18
going to happen and it's contractual.
7:26
You got to think of all three. We got to
7:28
discuss all three. If you go to my site,
7:29
you schedule a call, we'll go over all
7:31
three. What you can't run is a future
7:34
immediate annuity quote, right? No. But
7:37
you can run a a deferred income annuity
7:39
quote, defer it for whatever time you
7:41
want, and know exactly to the penny what
7:43
it's going to be. You can run an income
7:44
writer quote, defer it as long as you
7:46
want, know to the penny what it's going
7:47
to be.
7:50
The only one of those three choices
7:52
remember madpia income writer and dia
7:56
the only one that has a fee income
7:58
writer and that fee is taken out of the
8:01
index side so that it's a net
8:03
transaction to you. It does not
8:05
interrupt or lower the income guarantee.
8:11
It's it's really that simple. It is
8:13
simple. the industry and the agents
8:17
trying to push this stuff that don't do
8:19
it like I do make it so darn difficult
8:22
and muddy. And I think they do that for
8:24
a reason.
8:29
If you just remember this, when you're
8:31
looking for for income, if you just look
8:34
at the contractual guarantees, you're
8:36
going to be fine. Once you say, "What
8:38
what's the potential return on an index
8:40
annuity?" Then you're a fool. You're an
8:42
idiot. and someone's going to sell you
8:44
the dream and you're going to end up
8:46
owning the contractual realities and and
8:49
eventually that side of the ledger is
8:51
going to get cleaned up by somebody I
8:52
hope.
8:57
But income later, do you need income to
9:00
start at a future date? Then there's
9:01
three choices. Modia,
9:06
income writer, DIA. And of course, I've
9:09
done videos on all of those. If you go
9:12
to my YouTube channel, you can just type
9:13
into the space bar, the search bar,
9:16
migpia. There's videos on it. Income
9:19
writers, there's videos on it. I've done
9:21
comparison videos on all of all of
9:22
these.
9:25
But just do not allow someone to steer
9:27
you to one product that they go, well,
9:29
you know, I've looked at all of them and
9:30
this is the best one. Full of crap.
9:32
These people are full of crap.
9:36
And I'm hoping that they'll be wiped off
9:37
the board from the standpoint of them
9:39
being in the business in the near future
9:41
because
9:43
sites like mine that's 247 365. Sites
9:46
like mine that allow you to run quotes
9:48
anonymously and get the same quote.
9:50
Sites like mine that you could fill out
9:52
an application 247 365.
9:55
Sites like mine that give you an option
9:57
to talk to real people
9:59
or use technology. Either or. We are the
10:02
leader in annuity innovation. But it's
10:04
all customer driven. You I'm always
10:08
looking at how what would I want? If I
10:10
was going to come by an annuity, what
10:11
would I want? I would want to not give
10:13
up my personal information until
10:15
application time. We want you as a
10:17
client at then that point you have to.
10:18
But not until then. I'm going to keep my
10:20
powder dry. I'd want options. I'd want
10:22
to be able to do the application myself.
10:24
I'd want to talk if I want to talk to
10:26
Stan himself. I want to talk to Stan
10:28
himself. Or there's a virtual Stanley.
10:30
I'll just ask virtual Stanley.
10:32
So what we've done is we've given you
10:34
choices
10:37
but at the end the buck stops with me. I
10:39
own the company. So if you want to talk
10:41
with me you can but income later mispia
10:44
income writer dia. My name is Stan the
10:47
annuity man. That's shooting it straight
10:49
with Stan. I'll see you next time.
Talk to Stan The Annuity Man® himself
Get Stan for 30 minutes. No cost for his 3 decades of experience. Prepare yourself for the brutal annuity truth.